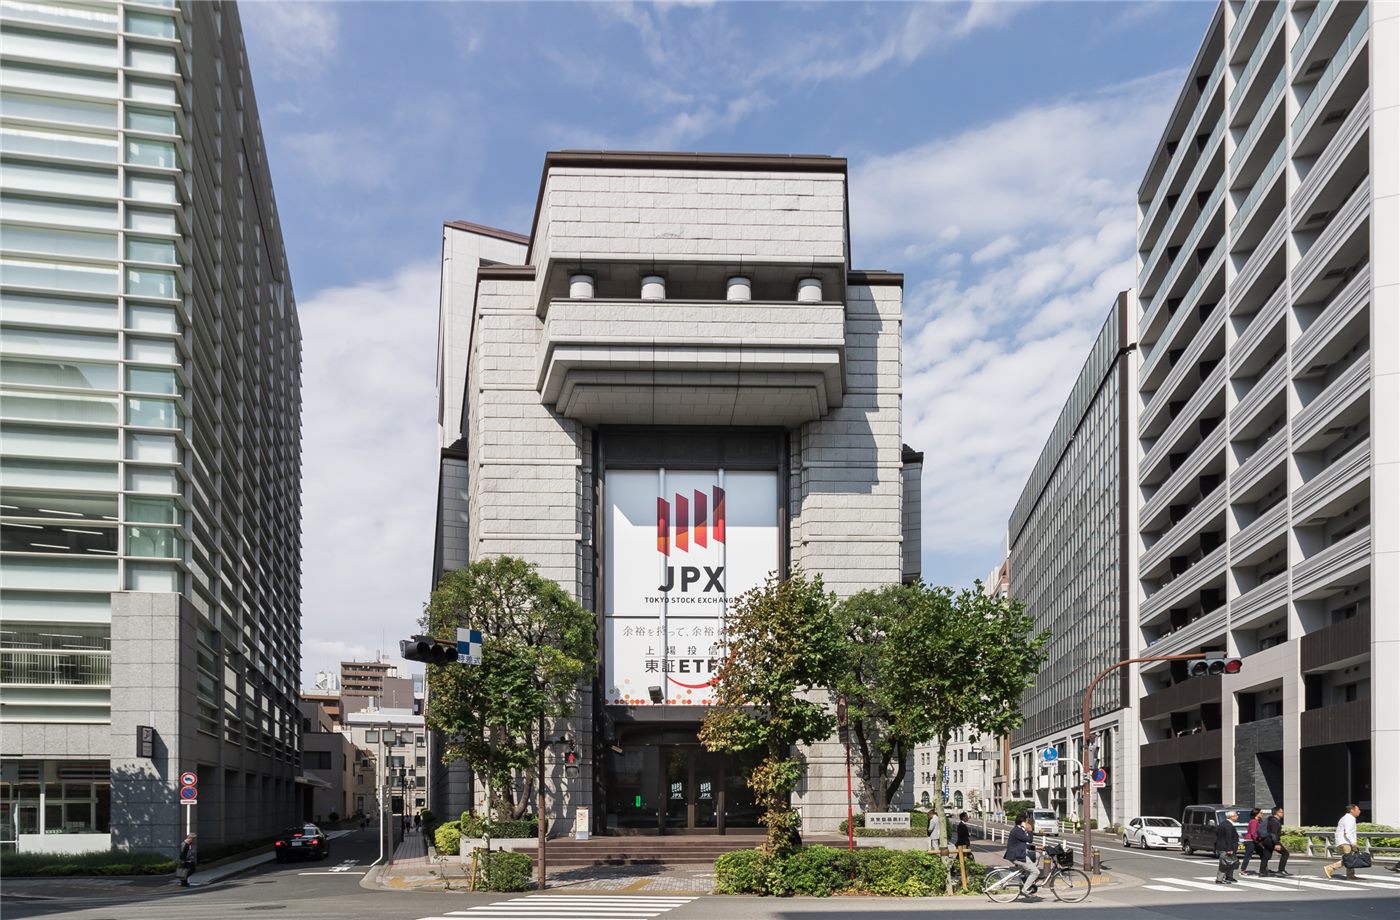
The Bank of Japan lifted its policy rate by a quarter point to 1.25 percent from 1.0 percent, yet the yen weakened to around 157 to the dollar. Two of the nine board members voted against the increase, reinforcing expectations that further tightening will be slow. Japan's currency authorities conducted a rate check with financial institutions, a warning that intervention is possible.
The Bank of Japan raised its benchmark rate by 0.25 percentage point to 1.25 percent at its policy meeting. Contrary to the textbook response in which higher rates strengthen a currency, the yen turned weaker against the dollar immediately after the announcement. It fell as much as 1.3 percent intraday toward 158 per dollar, with the decline settling near 157.09, about 0.7 percent lower.
광고 문의 · 300×250The main reason cited is that the market had already priced the increase in. The hike was treated as a foregone conclusion before the meeting, and attention had shifted from the size of the move to the timing of the next one. The disclosure that two of nine board members voted to hold rates steady strengthened the reading that there is no firm internal consensus on further tightening.
Japan's currency authorities began checking live quotes with major financial institutions. A rate check is a verbal-stage measure that commits no funds, but it is usually read as the step immediately preceding actual intervention. After the news circulated, the yen pared losses and traded near 156.70 per dollar, down 0.5 percent, in the New York afternoon.
Weakness that rate gaps alone do not explain
Even at 1.25 percent, the gap between Japanese rates and policy rates in the United States and other major economies remains wide. As long as the incentive persists to borrow a low-yielding currency and invest in higher-yielding assets, the market calculates that a small increase will not reverse capital outflows.
Flow factors compound the picture. Payments for energy and commodity imports, reinvestment of overseas subsidiary profits abroad, and retail purchases of foreign equities and funds all work in the direction of selling yen. The rate decision is only one axis; the weakness of real demand to buy yen has been noted for years.
The division of labor between the government and the central bank is another variable. The Bank of Japan sets rates, but authority over currency intervention rests with the Ministry of Finance. When monetary policy turns tighter while the exchange rate moves the other way, mixed signals from the two institutions tend to invite the market to test the gap.
What reaches Korea and Taiwan
A weaker yen translates into price pressure for exporters in Korea and Taiwan. The effect is sharpest in autos, machinery, materials and components, where firms compete head to head with Japanese rivals in third markets. Some analysts note that sensitivity has fallen from earlier episodes as semiconductors and information technology equipment have become the dominant export lines.
There are effects in the opposite direction. Companies importing Japanese parts and equipment see lower procurement costs, and travel demand to Japan rises. With Korea heading into the Chuseok holiday and Taiwan just past the Mid-Autumn Festival, demand for flights to Japan is high and the exchange rate feeds straight into consumer spending.
The spillover into Asian currencies generally is also watched. When the yen weakens, the won and the Taiwan dollar have repeatedly moved in sympathy. How far each authority tolerates volatility in its own currency is the thing to watch in Asian trading next week.
Markers to watch
First, whether intervention actually happens. Whether Tokyo stops at a rate check or moves to committing funds will set the near-term direction. Second, the central bank's next signal. Whether two dissenting votes reflect a passing disagreement or a crack in the policy stance should emerge from the governor's remarks and the summary of opinions.
Third, domestic prices and wages. A weaker yen pushes up import costs and erodes real household income. If wages fail to keep pace, consumption contracts, which itself makes a further increase harder to justify.
A third view: the exchange rate is a symptom, not a remedy
This paper does not read the episode solely as a test of currency defense. The direction of the yen is closer to a verdict on Japan's growth prospects and fiscal room, expressed in monetary form. A modest rate rise or a hint of intervention may slow the pace, but the widely held market view is that neither changes the direction.
The opposing view is just as clear. When speculative positioning becomes excessive, official intervention has broken the trend before, and doing nothing lets import-price surges hit low-income households first. On that reading, a rate check is a legitimate tool for preserving orderly markets.
For ethnic Chinese readers in Korea this is also a household matter. Remittances between the won and the yen, money moving to and from relatives in Japan, and holiday travel budgets are all tied to the rate. Foreign exchange practitioners advise sticking to basics such as staged conversion and spreading out settlement dates rather than chasing short-term swings.